All Categories
Featured
Table of Contents
Here's a breakdown of some of the most popular ones to consider: This method starts by listing your financial obligations from smallest to largest. Make minimum payments on all your cards while carrying any extra funds towards the smallest balance. As soon as you settle the smallest debt, you'll proceed to the next smallest and gain momentum with each victory.
It takes longer to pay off high-interest financial obligations. Those focused on fast wins and remaining determined Focus on paying off the debt with the highest interest rate.
Those focused on decreasing total interest paid and quicker general financial obligation decrease. This strategy integrates your card financial obligations into a single loan with a lower rate of interest. It can simplify your payments and save you cash on interest charges. There are two main choices: A personal loan is not backed by collateral, and approval depends on your credit reliability.
It requires excellent credit to certify, and interest rates are typically higher than those for guaranteed loans. Those with excellent credit who choose the simpleness of a single payment.
This option might provide lower interest rates than credit cards. Consolidating multiple debts can also simplify regular monthly payments. Unsecured loans typically require excellent credit to certify. A home equity loan puts your home at danger if you stop working to pay back. This technique is ideal for people with good credit who choose the simplicity of a single regular monthly loan payment.
Top-Rated 2026 Debt Relief Solutions for Families
Nevertheless, a number of other additional techniques can lower credit card financial obligation tension: While the minimum payment keeps your account in good standing, it won't considerably decrease your debt. Paying even a little additional each month will lower the quantity you owe much faster. If possible, set up automated payments above the minimum to make the procedure easier.
This can produce a vicious cycle of debt that's tough to escape. Think about keeping a couple of cards locked away or temporarily reducing your credit limitations as you reconstruct healthy costs habits.

A credit counseling course can supply important guidance if you discover it tough to handle several credit cards properly. If you're struggling, call the credit card provider and explain your scenario.
These services can be valuable if managing debt is frustrating or you need professional aid developing a payment technique. One of the fastest ways to deal with financial obligation is to make more cash.
You've paid off your credit cardnow what? Now that you have actually paid off your credit card, you may wonder about your next steps.
Seeking 2026 Financial Hardship Assistance
Even if you do not prepare on using the card frequently, keeping it open for emergency situation expenses could be useful.
Simply be mindful that it can momentarily lower your credit rating. You can use the funds to pay down other debts much faster.
Another choice, rather than paying down debt, is to construct up your savings. Redirecting charge card payments to savings can supplement your funds for vacations, big purchases, or emergency situation funds. Settling debt enhances your credit usage and can substantially boost your credit history. Credit bureaus monitor this metric to examine your credit use.
How to Reduce Credit Card Debt in 2026
If you're struggling to stay within your spending plan, consider designating your credit card for emergencies only. Comprehending how long to pay off a credit card can assist you make the necessary way of life modifications to reach your goal.
Analyze your costs practices and search for locations to cut down. Even small modifications with time can produce room in your budget for debt repayment. Be careful of services that promise to quickly eliminate your debt or dramatically settle it for a fraction of what you owe. These typically turn out to be frauds.
Proven Ways to Lower 2026 Credit Card DebtThis will only include more potential for spending and make the process harder. When used responsibly, credit cards can significantly enhance your credit rating. They also reveal the world you're responsible and take your financial health seriously. However, handling charge card financial obligation can be a significant monetary difficulty. Exploring credit card choices might provide the relief and control you need to restore your monetary footing.
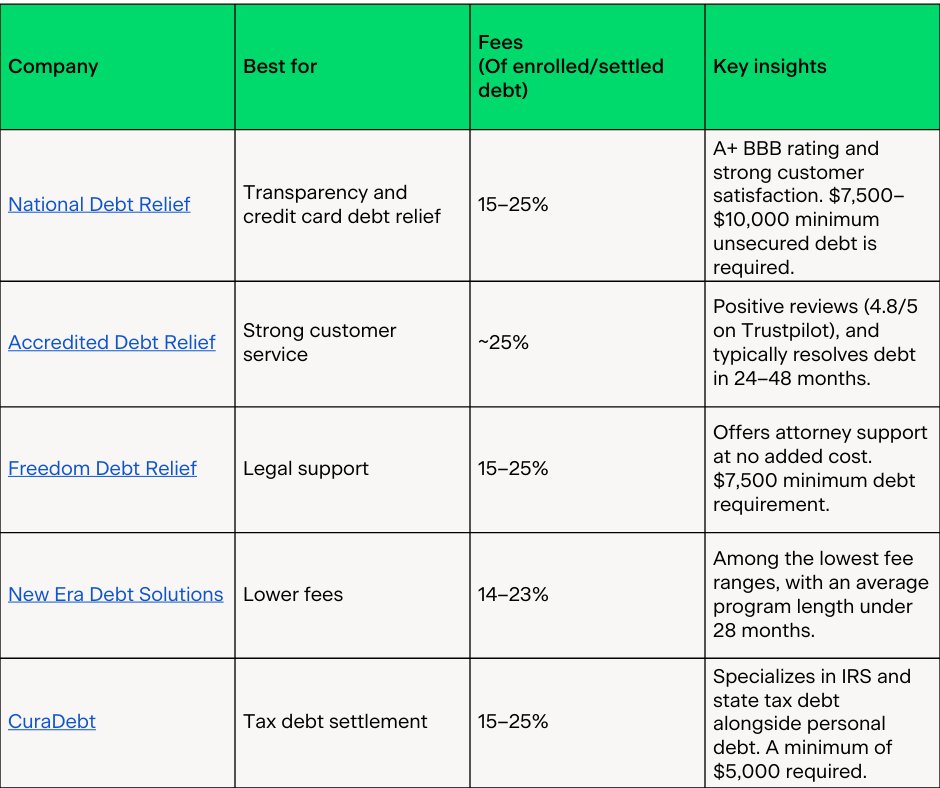
Devoting yourself to a method is the crucial to getting out of credit card financial obligation quick. We can't make your month-to-month credit card payments for you (actually, we kind of can with a personal loan), however we can reveal you how to get out of credit card debtfast!
If you have a $350 balance on a charge card with a 21-percent annual rate of interest, and you make a minimum payment of only $20 each month, it will take you 22 months to pay it off. That's nearly 2 years. If you double your payment to $40, you'll have the card paid off in only 10 months.
Will Debt Relief Help Your Credit Future?
This method ends up being even more valuable when you use it to even bigger balances. State you are making the minimum $90 payment on a card with a $2,750 balance and a 21 percent interest rate: You'll find yourself paying for the next 45 months (or 3.75 years). Yet, if you double the month-to-month payment, you'll run out financial obligation in just 18 months (1.5 years).

Latest Posts
Vital Tips to Reduce High-Interest Debt Quickly
How to Navigate Economic Hardship in 2026
How to Get 2026 Financial Hardship Assistance